
Three offers arrive. One has the highest price. The decision should be easy, right?
Not necessarily.
When sellers receive multiple offers, the purchase price naturally gets most of the attention. It is the biggest number on the page, and usually the first term everyone wants to compare.
But an offer is more than its price.
The strongest offer is often the one that gives the seller the best combination of net proceeds, favorable terms, and confidence that the transaction will actually make it to the closing table.
A Cash Offer With a Catch
I once represented a seller who received multiple offers, including one that appeared especially attractive: a full cash offer.
Cash is often treated as the gold standard in real estate. There is no mortgage approval, no lender-required appraisal, and usually less uncertainty surrounding financing.
At least, that is how it looks on the surface.
This particular cash offer was contingent upon the buyer selling a home in another state. That meant the buyer might not need a mortgage, but they did need another transaction to close before they could purchase my seller’s home.
I found the buyer’s property online and contacted the agent representing it. The home had already been on the market without receiving any offers.
Suddenly, that “cash” offer did not look quite as secure.
My seller also had a competing offer with financing. It was not the highest offer, and it did not carry the appeal of a cash purchase. But the buyer’s agent communicated well, the lender was responsive, and the financing had been carefully reviewed. The offer also included a pass/fail inspection contingency, which limited the likelihood of the buyer attempting to renegotiate after the inspection.
My seller accepted the financed offer.
The transaction closed on time, without surprises.
That outcome was not guaranteed, of course. No real estate transaction is. But once we looked beyond the labels and evaluated the risks, the lower financed offer gave the seller a clearer path to closing.
The Highest Price May Not Produce the Highest Proceeds
Purchase price and seller proceeds are not the same thing.
An offer may include seller-paid closing costs, buyer-agent compensation, repair allowances, extended occupancy, or other expenses that affect how much the seller ultimately receives.
The way an offer is structured can also make a difference.
I have represented buyers whose offers were accepted even though they did not have the highest purchase price. In one case, my buyer agreed to pay their own buyer-agent compensation. That structure reduced the amount incorporated into the purchase price and saved the seller additional money on transfer taxes. Once the seller looked at the actual proceeds—not just the headline price—the difference between the offers was much smaller than it initially appeared.
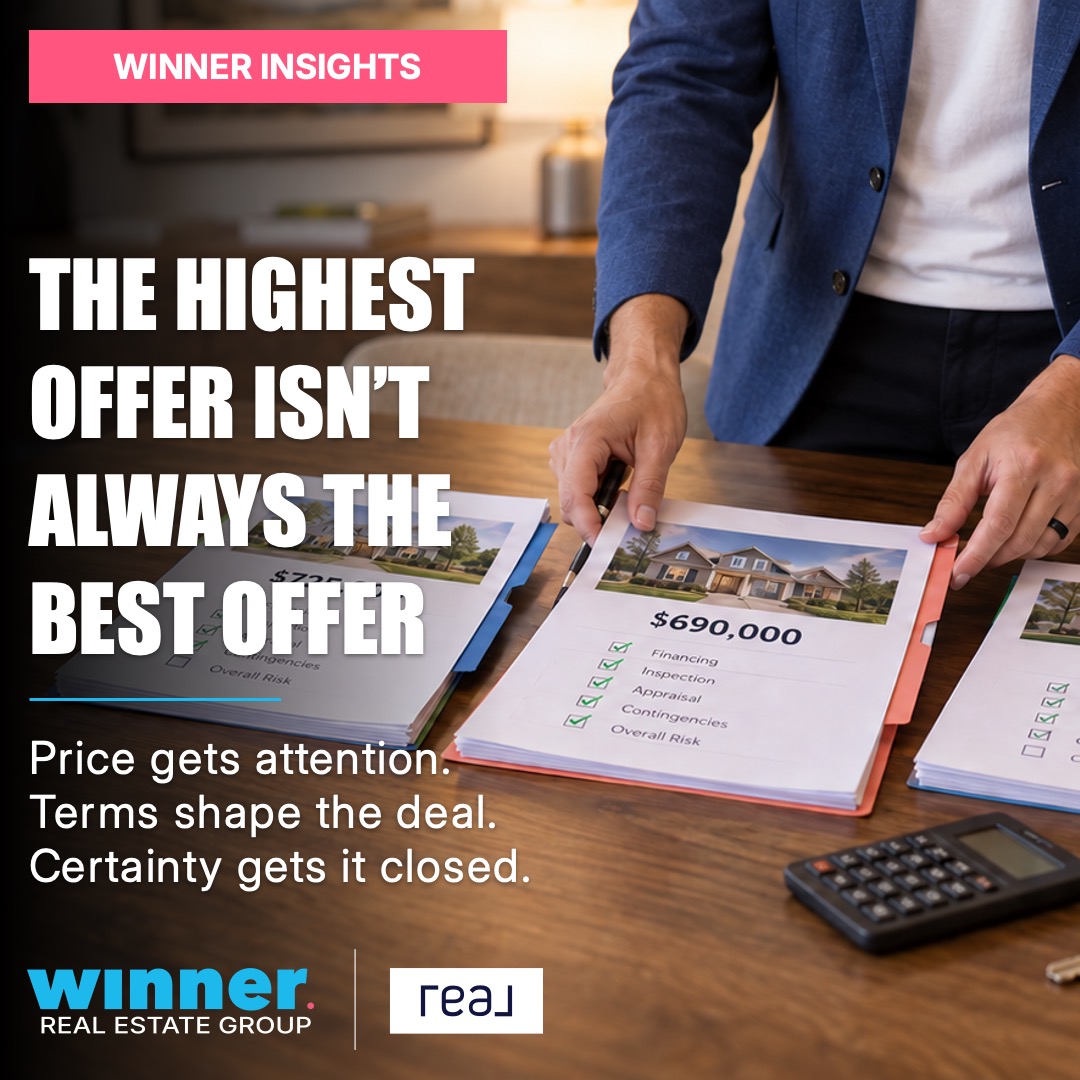
This is why I prepare a comparison table when my sellers receive multiple offers. It lays out the important terms side by side, including:
- Purchase price and estimated net proceeds
- Financing type and strength
- Seller concessions
- Inspection terms
- Appraisal protections
- Earnest money
- Closing timeline
- Occupancy
- Sale-of-home or other contingencies
I also include relevant information gathered through conversations with the buyer’s agent and lender. Internally, I weigh each component based on the risk it presents and the likelihood that the transaction will close.
The goal is not simply to identify the largest number. It is to help the seller understand what each offer could realistically mean from acceptance through closing.
A Preapproval Letter Is Only the Beginning
Nearly every financed offer arrives with a preapproval letter. That does not mean every preapproval carries the same weight.
When possible, I speak directly with the buyer’s loan officer. Without requesting the buyer’s confidential financial information, I want to understand how thoroughly the file has been reviewed.
Have the buyer’s income, assets, credit, and liabilities been verified? Has the file received additional underwriting review, or is the approval based primarily on an automated assessment? Is the buyer comfortably within the necessary debt-to-income limits, or are they close to the maximum? Will the property require a full appraisal, or has the buyer received an appraisal waiver?
Responsiveness matters, too.
If a lender does not return a call before an offer is accepted, it raises a reasonable question: How responsive will that lender be when an appraisal, underwriting condition, or closing deadline requires immediate attention?
The same is true of the buyer’s agent. Strong communication before acceptance does not guarantee a smooth transaction, but silence can be an early warning sign.
Inspection Terms Matter—But Waiving an Inspection Is Not the Only Option
A buyer does not always need to waive the inspection entirely to make an offer more attractive.
A pass/fail inspection allows the buyer to have the home professionally inspected and decide whether to proceed, but it typically removes the option to renegotiate over individual findings. The buyer can accept the property or terminate under the terms of the contingency.
Another option is to limit inspection negotiations to major defects. For example, a buyer might agree not to raise concerns unless a defect is expected to cost more than $5,000 to remedy.
These approaches can provide the buyer with meaningful protection while reducing the seller’s risk of being presented with a long repair request after the home is under contract.
By comparison, an extended inspection period can create more uncertainty. The longer the property is tied up, the more time the listing loses if the buyer ultimately walks away.
Inspection terms should be considered carefully by both parties. I rarely recommend that a buyer waive an inspection entirely unless the circumstances make it absolutely necessary and the buyer fully understands the risk.
The Cost of Choosing the Wrong Offer
Accepting a risky offer does not just mean the seller might have to start over.
If the transaction falls apart, the listing may return to the market with more days accumulated and a changed status history. Buyers may wonder what went wrong. Some may assume an inspection uncovered a serious problem, even when the actual issue involved financing or another unrelated contingency.
In the meantime, the seller may have made moving arrangements, packed belongings, scheduled contractors, secured another home, or planned financially around a closing that is no longer happening.
A higher offer provides little benefit if it ultimately costs the seller time, money, leverage, and another qualified buyer.
What This Means for Buyers
Buyers should not assume they are automatically out of the running because they cannot pay cash or submit the highest price.
A well-structured offer can compete.
Strong financing, a responsive lender, reasonable timelines, thoughtful inspection terms, and clear communication can make an offer more appealing without forcing the buyer to take unnecessary risks.
When I represent a buyer, I do more than send the paperwork and wait. I explain the offer to the listing agent—by phone or in person when possible—so they understand its strengths and can accurately communicate those advantages to the seller.
Sometimes the details that win an offer are not obvious on the first page.
The Best Offer Is the One That Works for the Seller
My job is to explain the advantages, costs, and risks of every offer and make a clear recommendation. The final decision always belongs to the seller, but I will tell my clients when I believe an offer presents more risk than its price suggests.
Selling a home is not an auction where the largest number automatically wins. It is a contract involving financing, deadlines, contingencies, people, and a long list of opportunities for something to go wrong.
The best offer is the one that delivers the strongest overall outcome—not just the most impressive purchase price.
Whether you are preparing to sell a home or trying to build an offer that stands out, the right strategy starts before anything is signed. Schedule a conversation, and let’s look at the numbers, the terms, and the risks together.

Comments are closed